As retirement approaches, the focus shifts from accumulating savings to turning those savings into sustainable income. Once the saving stage is complete, the main task becomes coordinating QPP, OAS, the Guaranteed Income Supplement (GIS), an employer pension, RRSP and RRIF withdrawals, TFSA use, pension splitting, income taxes, and the risks of longevity and inflation.
A larger monthly pension is not always the only objective. The order and timing of these income sources can significantly affect taxes and the amount of income available after tax, so each pension or account should be treated as part of one plan rather than a separate decision.
This guide explains how Quebec residents can coordinate their principal retirement income sources in 2026 to build a more sustainable, tax-aware retirement income.
When Should You Start QPP in Quebec: 60, 65 or 72?
In Quebec, the Quebec Pension Plan (QPP) is a core piece of retirement income, but on its own it typically does not replace full employment earnings. QPP is administered by Retraite Québec and runs separately from the Canada Pension Plan (CPP) used in the rest of Canada, though the two programs work in a similar way.
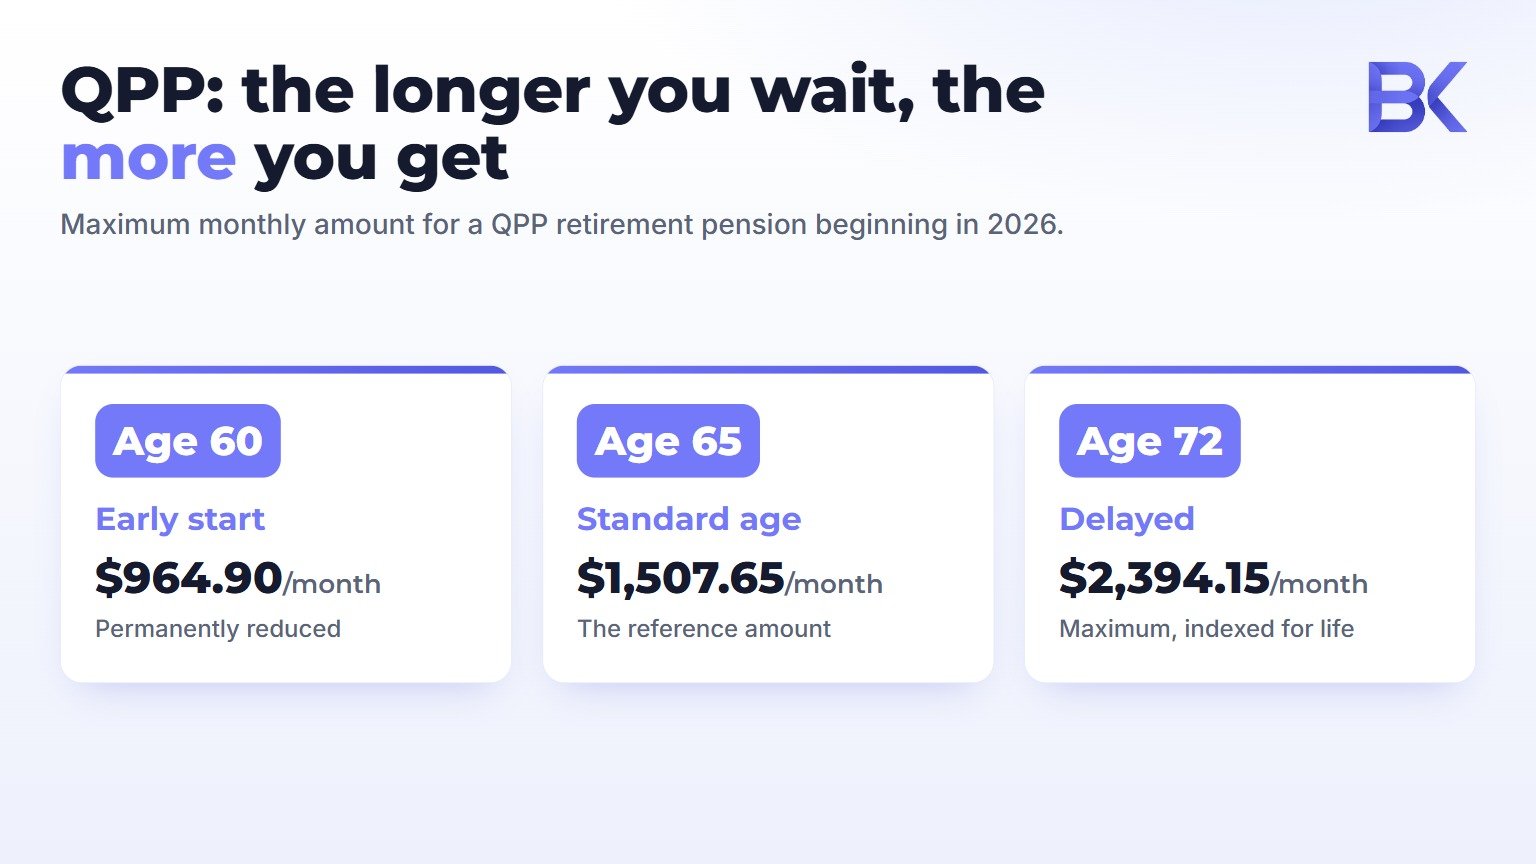
For pensions beginning in 2026, the maximum monthly QPP retirement pension is $1,507.65 at age 65. The maximum is $964.90 for a pension beginning at age 60 and $2,394.15 for one beginning at age 72.
These are maximum amounts, not typical payments. The actual pension depends on the contributor’s earnings history, contributions, periods excluded from the calculation, and the age at which the pension begins.
QPP Start Age Decisions
Starting QPP before age 65 permanently reduces the indexed monthly pension, while delaying it increases the amount payable for life. An early start may provide needed cash flow or place income in lower-tax years, but it also reduces the guaranteed lifetime income available later.
The decision should consider health, life expectancy, employment plans, available savings, other pension income, taxes, and the value of protecting against longevity and inflation risk.
The adjustment is permanent. Before age 65, the pension is reduced by approximately 0.5% to 0.6% for each month it starts early, depending on the pension amount. After 65, delaying QPP increases the pension by 0.7% per month, up to a maximum 58.8% increase at age 72.
QPP and Taxable Income
QPP benefits are taxable. If you already expect substantial pension income later on, starting QPP early can push more income — and more tax — into years when you may not need it.
Comparing an early, standard (around 65), and delayed start helps estimate lifetime income and tax efficiency, not just the size of the first monthly deposit.
| Start Timing | Monthly Benefit | Suited For |
| Early start (from age 60) | Lower monthly income | Those who need cash flow sooner |
| Around 65 | Standard benefit | A balanced approach |
| Delayed start (66 to 72) | Higher monthly income | Those with other assets and a longer time horizon |
OAS and GIS in Quebec: 2026 Amounts and Income Limits
Old Age Security (OAS) is a federal taxable pension that is separate from QPP. Eligibility and the amount payable depend partly on age and the number of years a person has lived in Canada after age 18.
For July to September 2026, the maximum monthly OAS pension is:
- $751.97 for individuals aged 65 to 74;
- $827.17 for individuals aged 75 and over.
These amounts are reviewed quarterly and may increase with changes in the Consumer Price Index. A person who has not lived in Canada for the period required to receive a full pension may receive a partial amount.
Starting OAS at 65 or Delaying It
OAS can begin at age 65 or be delayed until age 70. The payment increases by 0.6% for each month of delay, or 7.2% per year, up to a maximum increase of 36% at age 70.
Delaying OAS may be appropriate for someone who has other assets, expects a long retirement, and wants more indexed lifetime income later. It is generally not beneficial for a person who qualifies for the Guaranteed Income Supplement, because GIS eligibility requires the person to receive OAS. Delaying OAS would normally delay GIS as well.
The Guaranteed Income Supplement
GIS is a non-taxable, income-tested benefit available to eligible low-income OAS recipients. The amount depends on marital status and on the previous year’s income.
For July to September 2026:
- a single, divorced, or widowed person may receive up to $1,123.17 per month when annual income, excluding OAS, is below $22,800;
- a person whose spouse receives a full OAS pension may receive up to $676.09 per month when the couple’s combined income is below $30,096.
Different limits apply when a spouse receives the Allowance or does not receive OAS. Because the amounts and thresholds are indexed, current figures should always be confirmed before making a decision. Official amounts and eligibility rules are published by the Government of Canada’s Old Age Security program.
Important planning note: GIS is normally calculated using income from the previous year. However, if your or your spouse’s income drops because of retirement or because pension income is reduced or stops, Service Canada may be able to calculate your benefit using an estimate of current-year income instead. This can be important in the first year of retirement, when last year’s employment income no longer reflects your current financial situation.
OAS Recovery Tax
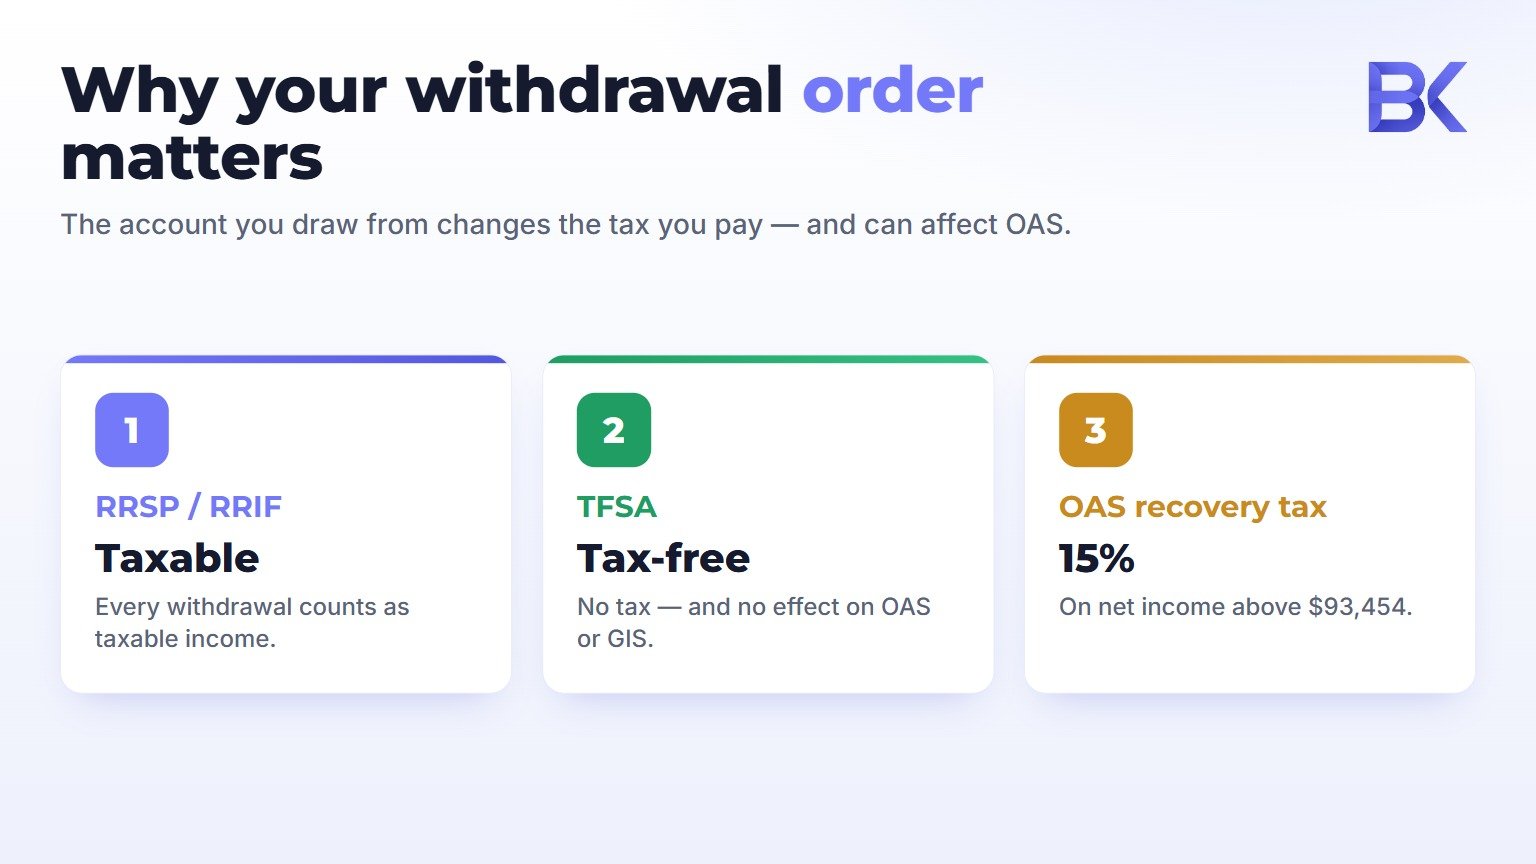
OAS is subject to a recovery tax when your net income before adjustments exceeds the applicable threshold. For OAS payments from July 2026 to June 2027, the calculation is based on 2025 income, and the minimum recovery threshold is $93,454. The recovery tax is generally 15% of income above that threshold.
For retirement-income decisions made during 2026, another number matters: 2026 income will determine the recovery tax applied to OAS payments from July 2027 to June 2028, and the minimum recovery threshold for 2026 income is $95,323.
Additional RRSP or RRIF withdrawals, employment income, investment income, QPP benefits and employer-pension income can therefore affect OAS recovery. When planning withdrawals, it is important to look at the income year that will determine the future recovery period, not only the OAS amount being received today.
Why Withdrawal Order Matters
RRSP and RRIF withdrawals are taxable and can reduce GIS or trigger OAS recovery tax. TFSA withdrawals are tax-free and do not affect OAS, GIS, or other federal income-tested benefits.
That does not mean a retiree should always preserve the RRSP and spend the TFSA first. Someone in a temporarily low tax bracket may benefit from making planned RRSP withdrawals before QPP, OAS, or mandatory RRIF payments begin. This can reduce the future registered balance while preserving the TFSA for later expenses or years when keeping taxable income low becomes more important.
A retirement-income projection should therefore compare:
- starting OAS at 65 versus delaying it;
- the likelihood of qualifying for GIS;
- planned RRSP withdrawals before age 71;
- future RRIF minimums;
- possible OAS recovery tax;
- the use of TFSA withdrawals for large or irregular expenses.
Employer Pensions and QPP Integration in Quebec
An employer pension should be analyzed together with QPP, OAS, RRSP, TFSA, and other retirement assets. The first step is to identify whether the plan is a defined-benefit plan or a defined-contribution plan.
A defined-benefit pension generally promises income based on a formula involving earnings and years of service. A defined-contribution plan accumulates contributions in an account, and the eventual retirement income depends on the account balance, investment performance, fees, and the income option selected at retirement.
Information to Confirm Before Choosing a Retirement Date
Review the plan statement and obtain answers to the following questions:
- What is the plan’s normal retirement age?
- Is there a permanent reduction for starting the pension early?
- Is the pension fully, partially, or not indexed?
- Does the plan provide a temporary or bridge benefit before age 65?
- Does the monthly payment decrease at age 65?
- Is the plan integrated or coordinated with QPP?
- What survivor-pension percentage applies?
- Does choosing a larger survivor benefit reduce the member’s initial pension?
- Are transfer or commuted-value options available?
- What happens to health, dental, or life-insurance benefits after retirement?
QPP Integration in Quebec Public-Sector Plans
Some Quebec employer pension plans, including major public-sector plans such as RREGOP, are integrated with QPP. Under RREGOP, the pension is reduced as of the month following the member’s 65th birthday to reflect QPP integration.
This reduction applies regardless of whether the person started QPP before age 65 or decides to delay QPP until later. In other words, the QPP start date and the RREGOP integration date are separate decisions. A retiree who delays QPP beyond 65 should therefore plan for the fact that the RREGOP pension can still decrease at 65, potentially creating a temporary income gap.
Do not assume that the pension amount shown at age 60 will continue unchanged for life. Retirement projections should show the employer pension separately before and after age 65, and again in the year QPP begins — the full staged breakdown is covered later in this guide.
Working After 65: Can You Stop QPP Contributions?
Receiving a QPP retirement pension does not prevent a person from continuing to work. If employment or self-employment income exceeds $3,500, QPP contributions generally continue and create an additional retirement pension supplement.
The supplement is added automatically beginning in the year after the contributions are made. It is payable for life and is indexed. The annual supplement is generally equal to 0.66% of the employment earnings on which the person contributed for the preceding year, subject to the applicable earnings limits.
Choosing to Stop Contributions
A worker who is at least 65 but under 73 and is already receiving a QPP or CPP retirement pension may elect to stop contributing.
For an employee, the election is made using form RR-50-V. The form is sent to Revenu Québec and a copy is given to each affected employer. The election generally takes effect beginning with the first pay of the month following the month in which the employer receives the form.
A self-employed person makes the election through Schedule U of the Quebec income tax return and may reconsider the decision in a later year.
QPP contributions stop automatically as of January 1 following the worker’s 72nd birthday.
Continue or Stop Contributions?
Continuing contributions may be attractive when:
- the worker is an employee and the employer pays an equal contribution;
- a larger indexed lifetime pension is a priority;
- the person expects a long retirement;
- current cash flow is sufficient.
Stopping contributions may be considered when:
- immediate disposable income is more important;
- the person is self-employed and must pay both the employee and employer portions;
- health or life-expectancy considerations reduce the value of a future lifetime supplement;
- the worker already has sufficient guaranteed pension income.
The decision should compare the current cost of contributions with the projected lifetime, indexed supplement rather than viewing the contribution only as a payroll deduction.
Building a Pension Income Strategy
A pension income strategy is really about managing the order you draw from your accounts, not just their balances. Many Quebec retirees have several income sources — QPP, OAS, RRSP/RRIF, TFSA, and employer pensions — but draw from them inefficiently, which can push taxes higher than necessary.
The right withdrawal sequence depends on factors like retiring early, having a defined-benefit pension, or an income gap between spouses.
RRSP to RRIF Conversion at Age 71
An RRSP must mature no later than December 31 of the year you turn 71. At that point, you can withdraw the funds, transfer them to a RRIF, use them to purchase an eligible annuity, or use a combination of the available options.
If you establish a RRIF, minimum annual withdrawals begin in the following calendar year. Planning withdrawals from an RRSP before age 71 — or converting part or all of it to a RRIF earlier when appropriate — can sometimes help spread taxable income over more years and reduce the risk of large mandatory taxable withdrawals later.
Pension Income Splitting in Quebec
Eligible pension-income splitting allows one spouse or common-law partner to allocate up to 50% of qualifying pension income to the other for tax purposes. Federally, certain life annuity payments from a registered pension plan may qualify even when the pensioner is under age 65. RRIF, LIF, and RRSP annuity payments generally qualify once the transferring spouse is age 65 or older, subject to the applicable rules.
Quebec applies a separate provincial election. In general, the spouse transferring retirement income must be age 65 or older at the end of the year, and Schedule Q must be completed. As a result, the amount that can be transferred on the Quebec return may differ from the amount split federally.
QPP and OAS payments are not eligible for the regular federal or Quebec pension-income-splitting elections. However, eligible Quebec couples may apply for a separate QPP retirement-pension-sharing arrangement through Retraite Québec. Both spouses must generally be at least age 60, and additional conditions apply. The pension is shared according to the period during which the spouses lived together, so it is not necessarily divided equally.
Because Quebec generally restricts retirement-income transfers until age 65, some couples use a spousal RRSP during their working years to help balance future taxable retirement income. A spousal RRSP therefore needs to be planned well in advance. In general, if the contributing spouse made contributions to any spousal RRSP in the year of the withdrawal or either of the two preceding calendar years, attribution rules may cause some or all of the withdrawal to be taxed back to the contributor, subject to the applicable exceptions.
Illustrative Scenario: A Professional Approaching Retirement
The following simplified example is provided for educational purposes only. It does not describe an actual client, and all figures are hypothetical. Actual results depend on investment returns, inflation, tax rules, pension entitlements, fees, life expectancy, and personal circumstances.
A 52-year-old Montreal professional earns approximately $165,000 per year. He has:
- $115,000 in an RRSP;
- $32,000 in a TFSA;
- no defined-benefit employer pension;
- approximately $175,000 remaining on his mortgage;
- a target retirement age of 65.
His initial concern was that he had started saving too late. However, the more important issue was the lack of coordination between his remaining high-income working years and his future withdrawal years.
The planning process compared several elements:
- claiming larger RRSP deductions while his marginal tax rate remained high;
- directing part of the resulting tax savings to his TFSA and mortgage;
- estimating the spending level his savings would need to support;
- comparing QPP starting at ages 65, 70, and 72;
- estimating OAS and possible recovery tax;
- considering planned RRSP withdrawals during lower-income years before mandatory RRIF withdrawals began.
Rather than maximizing the RRSP without a future withdrawal plan, the strategy balanced RRSP contributions with TFSA savings and debt reduction. The projection also included a controlled drawdown of registered savings during lower-income retirement years.
The result was not a guaranteed tax saving, but a clearer retirement target, a more diversified source of future income, and a lower projected concentration of taxable RRIF withdrawals under the assumptions used.
Putting the Retirement Income Plan Together
A retirement income strategy should show how income changes at each important stage, rather than presenting only one average annual amount. The average income across an entire retirement is far less useful than a year-by-year projection.
The projection should distinguish:
- the first years immediately after employment ends;
- the period before QPP begins;
- the period before OAS begins;
- the year an employer bridge pension ends;
- any reduction in an employer pension due to QPP integration;
- the year QPP begins;
- the year OAS begins;
- the beginning of mandatory RRIF minimum withdrawals;
- the years when pension splitting becomes available;
- the use of TFSA withdrawals for larger or irregular expenses.
This staged approach helps identify temporary income gaps, future tax increases, possible OAS recovery tax, and years in which planned RRSP withdrawals may be advantageous. Because Quebec residents file with both the Canada Revenue Agency and Revenu Québec, retirement income is taxed under two systems — one more reason to plan withdrawals with both returns in mind. It also helps to see how these decisions connect with your broader financial picture, including how we approach investment planning for Quebec clients.
FAQ
1. Is QPP enough to fund retirement in Quebec?
For most people, QPP alone will not replace their full employment income. Retirement income may also come from OAS, an employer pension, RRSP or RRIF withdrawals, TFSA savings, and non-registered investments.
2. When should I start receiving QPP?
The appropriate age depends on health, life expectancy, employment plans, available savings, other pension income, and the value placed on receiving a larger indexed lifetime pension.
3. Should I start OAS at age 65 or delay it?
OAS may be delayed until age 70 in exchange for a higher monthly payment. The decision should consider life expectancy, other available income, tax exposure, and possible GIS eligibility.
4. When must an RRSP be converted to a RRIF?
An RRSP must be converted to a RRIF, used to purchase an eligible annuity, or withdrawn no later than the end of the calendar year in which the owner turns 71.
5. How do RRSP and RRIF withdrawals affect taxes?
RRSP and RRIF withdrawals are taxable income. Larger withdrawals may increase the marginal tax rate, reduce income-tested benefits, or trigger OAS recovery tax.
6. Can QPP income be split between spouses?
QPP does not qualify for the regular federal or Quebec pension-income-splitting elections. However, eligible couples may apply for a separate QPP retirement-pension-sharing arrangement through Retraite Québec.
7. Which retirement income can be split for tax purposes?
Depending on age and the applicable federal and Quebec rules, eligible income may include certain employer pensions, RRIF or LIF payments, and eligible annuity income. QPP and OAS payments are not included in the regular pension-income-splitting elections.
8. What is the OAS clawback threshold in 2026?
For OAS payments from July 2026 to June 2027, the recovery tax is based on 2025 income and begins above $93,454. For income earned in 2026, the minimum recovery threshold is $95,323; that income will affect OAS payments for the July 2027 to June 2028 recovery period.
9. Can I stop contributing to QPP after age 65?
If you are at least 65 but under 73 and already receive a QPP or CPP retirement pension, you may be able to elect to stop QPP contributions while continuing to work. Employees use form RR-50-V, while self-employed individuals make the election through Schedule U of the Quebec return.
Already Building Your Retirement Savings?
Still deciding how to build your retirement capital? If you are in the saving stage and weighing where to direct each dollar, read our guide comparing RRSP and TFSA strategies in Quebec.
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute individualized financial, tax, investment, or legal advice. It is based on rules and amounts in effect on July 27, 2026, which may change as programs, contribution limits, and tax legislation are updated. Any strategy should be evaluated in light of your personal financial situation, objectives, and tolerance for risk. Consult a qualified financial professional before making decisions.
Build a More Sustainable Retirement Income Strategy
Review how QPP, OAS, GIS, employer pensions, RRSP and RRIF withdrawals, TFSA savings, and pension splitting work together.
Boris Kolodner, MBA, Financial Planner and Licensed Financial Security Advisor, helps Quebec residents compare retirement dates, pension start options, withdrawal sequences, and projected after-tax income.
Book a free consultation:
Phone: +1-514-834-5558
Email: contact@bkfinancialservices.ca
Website: bkfinancialservices.ca
Consultations are available in English, French, Russian, and Hebrew.